RE/MAX entered 2026 with continued pressure on revenue and profitability, driven primarily by lower U.S. agent count, changes to its fee structures, and higher operating costs. Total revenue fell 5.7% to $70.2 million, while Adjusted EBITDA declined 19.3% to $15.6 million and the company reported a GAAP net loss attributable to RE/MAX Holdings of $9.7 million. Despite this, total global agent count increased 2.1%, supported by strong growth outside the U.S. and Canada, while Canada also posted modest agent growth. Strategically, the quarter was dominated by the announced merger with The Real Brokerage, which management expects to create a technology-enabled global real estate platform under the Real REMAX Group name. While the merger is pending, RE/MAX has suspended formal guidance and quarterly earnings calls, making the near-term outlook more focused on transaction completion, integration potential, agent retention, technology investment, and stabilizing the core U.S. business.
Key Financial Highlights
First-quarter revenue was $70.2 million, down 5.7% from $74.5 million a year earlier. Revenue excluding the Marketing Funds was $53.4 million, down 4.0%, including negative organic revenue growth of 4.7%, partially offset by a 0.7% benefit from foreign exchange. The decline was driven mainly by changes to standard fee models, including Aspire and Ascend, and lower U.S. agent count.
Recurring revenue from continuing franchise fees and annual dues declined 10.2% and represented 62.5% of revenue excluding the Marketing Funds, down from 66.8% a year earlier.
Adjusted EBITDA fell 19.3% to $15.6 million, while Adjusted EBITDA margin declined to 22.2% from 25.9%. Adjusted EPS fell to $0.16 from $0.24.
On a GAAP basis, RE/MAX reported a $15.7 million consolidated net loss, with a $9.7 million net loss attributable to RE/MAX Holdings, compared with a $2.0 million attributable loss in Q1 2025. GAAP diluted EPS was $(0.48).
Cash and cash equivalents were $107.1 million at quarter-end, while outstanding debt remained high at approximately $436.0 million. Operating cash flow was negative $1.8 million, and adjusted free cash flow was negative $5.4 million.
Strategic Initiatives and Market Performance
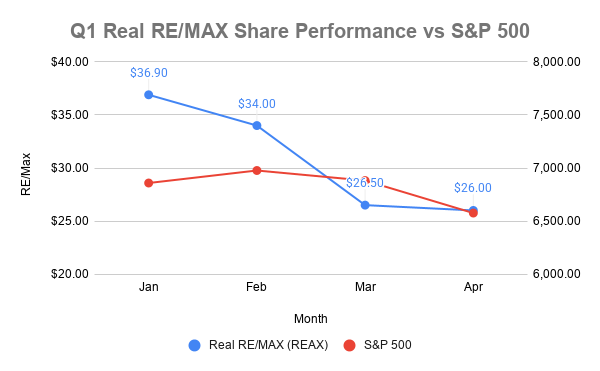
The most significant strategic development was the announced transaction with The Real Brokerage. On April 26, 2026, RE/MAX entered into a definitive merger agreement under which Real would acquire RE/MAX Holdings and create Real REMAX Group, intended to become a technology-enabled global real estate platform.
Beyond the merger, RE/MAX continues to emphasize modernization of its franchise economics and technology platform. The company’s forward-looking discussion specifically references its Aspire and Ascend economic models, Marketing Studio platform, technology initiatives, efforts to enhance its value proposition, and investments aimed at improving the experience for agents and franchisees.
Agent performance was mixed. Total global agent count increased 2.1% to 149,192, but the composition matters:
- U.S. agents declined 4.8% to 47,443.
- Canada increased 2.8% to 25,849.
- Agents outside the U.S. and Canada increased 6.7% to 75,900.
That means RE/MAX continues to grow internationally while its largest domestic market remains under pressure.
Challenges
The primary operating challenge is the continued decline in the U.S. agent base, which fell 4.8% year over year. This negatively affected recurring franchise economics and contributed to weaker revenue.
RE/MAX is also dealing with pressure from its revised fee models. Management specifically states that the Aspire and Ascend programs contributed to lower organic revenue, even though some of that impact was partly offset by higher broker fees.
Profitability deteriorated as expenses increased. Total operating expenses rose 13.0% to $78.1 million, while selling, operating and administrative expenses increased 8.8%. The increase was driven by merger-related transaction costs, annual agent-convention expenses, and higher technology investment. Settlement and impairment charges were also significant at $8.5 million, while merger transaction costs added another $2.8 million to adjusted results.
Another important challenge is leverage. RE/MAX ended the quarter with roughly $436 million of debt, which remains substantial relative to its earnings base. Interest expense was $7.2 million in the quarter, adding pressure to GAAP profitability and cash flow.
Outlook
RE/MAX did not provide quarterly or annual guidance because of the pending merger with The Real Brokerage, and it also suspended quarterly earnings calls while the transaction was pending.
The near-term outlook is therefore tied heavily to the merger process and integration potential. Key strategic questions include whether the combined company can achieve expected synergies, improve leverage, integrate RE/MAX effectively into Real’s technology platform, and retain agents, franchisees, and employees through the transition. The company specifically identifies those issues as risks and expected areas of focus.
Operationally, the key items to monitor are whether U.S. agent declines stabilize, whether Aspire and Ascend improve long-term franchise economics after their initial revenue impact, whether technology investment begins to produce better operating leverage, and whether international agent growth can offset domestic weakness.
Overall, Q1 2026 looks less like a normal standalone quarter and more like a transition quarter: the underlying RE/MAX business remained under pressure, particularly in the U.S., while management’s strategic attention shifted toward completing the Real merger and positioning the combined company for a more technology-enabled and globally scaled operating model.