The 2025 annual report reflects The Real Brokerage as a standalone company prior to its 2026 combination with RE/MAX Holdings. Accordingly, the report provides the clearest view of Real’s strategy, financial performance, and operating model before the two businesses became part of the same corporate group.
The central message Real wants shareholders to take away is: the company believes it has proven that its model can gain market share and scale even in a very weak housing market, and it is building the platform now so that it can benefit disproportionately when housing activity eventually recovers. CEO Tamir Poleg describes 2025 as a “breakthrough year,” pointing to 56% revenue growth to nearly $2.0 billion, 44% gross-profit growth, more than 185,000 transactions, $62.9 million of Adjusted EBITDA, $66 million of operating cash flow, and $39 million returned through share repurchases while maintaining a debt-free balance sheet.
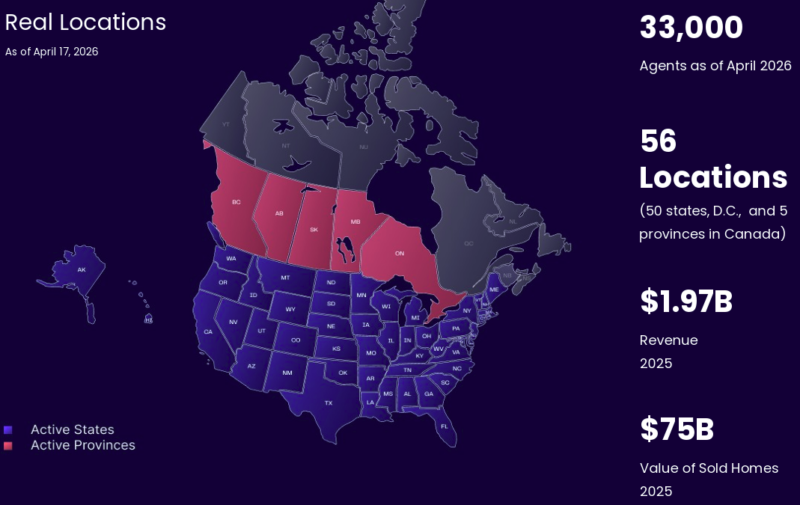
A particularly important part of the shareholder story is that this growth occurred despite housing activity remaining near cyclical lows. Real wants investors to view the company’s growth as market-share capture rather than simply benefiting from a strong real estate cycle. Agent count reached 31,739 at year-end, up 31%, and roughly 85% of agent growth came from existing agents attracting other agents. Management also emphasizes that its agents are productive and staying with the platform, with revenue churn near record lows.
What Real is telling shareholders
The basic investment thesis being communicated is:
“We are taking share while the market is weak, our technology lets us scale more efficiently than traditional brokerages, and we are building higher-margin businesses around the brokerage so that Real becomes more valuable per agent and per transaction over time.”
That is visible in the 2025 results. Revenue increased 56%, transactions increased 54%, the value of homes sold increased 53%, and operating cash flow increased 35%.
Management also wants shareholders to look beyond GAAP profitability alone. Real remained loss-making for the full year, with an $8.1 million net loss, but that was substantially better than the $26.5 million loss in 2024. Gross profit rose from $114.7 million to $165.7 million, while the operating loss narrowed from $25.2 million to $9.2 million.
Real’s strategy for 2026
1. Keep aggressively growing the agent base and taking brokerage market share.
This remains the foundation of the model. Management says 2025 performance was primarily driven by continued organic growth in productive agents and transaction volume despite muted industry conditions. Real believes its combination of economics, revenue sharing, equity incentives, culture, and technology can continue pulling agents away from traditional competitors.
The company is effectively pursuing a land-grab strategy while the overall industry is weak: expand the agent network now so that when transaction volumes recover, a much larger number of Real agents participate in that recovery.
2. Use AI and automation to scale without matching agent growth with headcount growth.
Technology is increasingly central to the economics of the company, not simply an agent recruiting tool. In 2025, Leo CoPilot exceeded 700,000 agent interactions and autonomously handled approximately 46% of support volume during the second half of the year. Real says its AI automation team also created workflows that saved thousands of employee hours.
That matters because management’s goal is to increase revenue and transactions significantly faster than fixed operating costs. The MD&A explicitly says proprietary technology and automation are intended to let the business scale without a proportional increase in fixed expenses and that management is balancing growth investment with disciplined cost management to improve operating leverage.
3. Expand from an agent platform into a consumer-facing real estate platform through HeyLeo.
One of the biggest strategic changes is Real’s movement closer to the consumer. The company acquired AI-powered home-search technology from Flyhomes in 2025 and beta-launched HeyLeo.com in selected states during Q4.
The ambition is broader than home search. Real describes the transaction lifecycle—from initial consumer search through final commission payment—as being rebuilt on its platform. That could allow Real to own more of the customer journey rather than simply serving as the back-end brokerage for agents.
4. Increase ancillary-service attachment to raise revenue and margins per transaction.
This may be the most important financial strategy beyond agent growth. Real is investing in One Real Mortgage, One Real Title, and Real Wallet because management believes those businesses can eventually produce materially higher gross margins than brokerage commissions.
Those businesses generated $11.9 million of combined revenue in 2025. Real Wallet alone produced nearly $900,000 in revenue, had more than 7,000 active agents, roughly $23 million in deposits, and more than $8 million of credit lines extended to agents. Management says these services also create switching costs that can deepen agent loyalty.
For 2026, therefore, success should not be measured only by how many agents Real adds. A key metric will be how much additional mortgage, title, wallet and related revenue Real captures from transactions already flowing through its brokerage.
5. Improve margins, cash generation and capital efficiency while continuing to invest.
Real’s core brokerage economics have a structural issue: highly productive agents eventually reach their annual commission caps, after which Real earns fixed transaction fees rather than its percentage commission split. Greater agent productivity therefore actually creates near-term pressure on brokerage gross margins. Management explicitly notes this effect in the annual report.
The solution is not to discourage productivity. Instead, Real intends to offset that margin pressure through scale, automation, and higher-margin ancillary services. Management says ancillary revenue growth and attachment rates will be important drivers of long-term margin expansion.
Capital allocation also matters. Real generated $65.9 million of operating cash flow in 2025 and spent $39.4 million repurchasing shares. It also maintains a share-repurchase authorization allowing it to buy up to the lesser of 35 million shares or $150 million.
The key tension in 2026
There is one important issue shareholders should watch: Real is growing rapidly, but the business has not yet demonstrated sustained GAAP profitability. The company posted its first positive GAAP net-income quarter during 2025, but remained loss-making for the full year. Stock-based compensation was also substantial at $68.1 million, up from $52.9 million in 2024.
The ancillary businesses are also still losing money while Real invests in them. Management believes they can eventually deliver higher margins, but 2026 is likely to be an important year for demonstrating that mortgage, title and fintech can move from being growth investments toward meaningful contributors to overall profitability.